 Poradmin
$10,000 of cash (asset) will be received from the bank but the business must also record an equal amount representing the fact that the loan (liability) will eventually need to be repaid. The accounting equation is fundamental to the double-entry bookkeeping https://www.bookstime.com/ practice. Its applications in accountancy and economics are thus diverse. These are some simple examples, but even the most complicated transactions can be recorded in a similar way. This equation is behind debits, credits, and journal entries.
This transaction affects only the assets of the equation; therefore there is no corresponding effect in liabilities or shareholder’s equity on the right side of the equation. The double-entry practice ensures that the accounting equation always remains balanced, meaning that the left-side value of the equation will always match the right-side value. Revenues and expenses are often reported on the balance sheet as “net income.” Take this quick test on accounting equations to help you prepare for your exams, interviews, or different tests. The business has paid $250 cash (asset) to repay some of the loan (liability) resulting in both the cash and loan liability reducing by $250.
Every transaction is recorded twice so that the debit is balanced by a credit. As you can see, all of these transactions always balance out the accounting equation. This equation holds true for all business activities and transactions. If assets increase, either liabilities or owner’s equity must increase to balance out the equation. The accounting equation equates a company’s assets to its liabilities and equity.
These are fixed assets that are usually held for many years. Assets include cash and cash equivalents or liquid assets, which may include Treasury bills and certificates of deposit (CDs). Below is a portion of Exxon Mobil Corporation’s (XOM) balance sheet as of September 30, 2018. By decomposing equity into component parts, analysts can get a better idea of how profits are being used—as dividends, reinvested into the company, or retained as cash. Adam Hayes, Ph.D., CFA, is a financial writer with 15+ years Wall Street experience as a derivatives trader. Besides his extensive derivative trading expertise, Adam is an expert in economics and behavioral finance.
Metro purchased supplies on account from Office Lux for $500. For the past 52 years, Harold Averkamp (CPA, MBA) hasworked as an accounting supervisor, manager, consultant, university instructor, and innovator in teaching accounting online. He is the sole author of all the materials on AccountingCoach.com. To learn more about the balance sheet, see our Balance Sheet Outline.
Now that we have a basic understanding of the equation, let’s take a look at each accounting equation component starting with the assets. For every transaction, both sides of this equation must have an equal net effect. Below are some examples of transactions and how they affect the accounting equation.
There are different categories of business assets including long-term assets, capital assets, investments and tangible assets. They were acquired by borrowing money from lenders, receiving cash from owners and which of the following is the basic accounting equation? shareholders or offering goods or services. The combined balance of liabilities and capital is also at $50,000. Ted is an entrepreneur who wants to start a company selling speakers for car stereo systems.
Poradmin
It can be considered as a cash version of the net income of a company since it starts with the net income or loss, then adds or subtracts from that amount to produce a net cash flow figure. https://www.bookstime.com/ Let’s say we’re creating a cash flow statement for Greg’s Popsicle Stand for July 2019. But here’s what you need to know to get a rough idea of what this cash flow statement is doing.
Therefore, cash is not the same as net income, which includes cash sales as well as sales made on credit on the income statements. Add the net cash flows from operating, investing, and financing activities to determine the overall change in cash and cash equivalents for which of the following is something you could find using the cash flow statement? the period. Investing activities include any sources and uses of cash from a company’s investments. Purchases or sales of assets, loans made to vendors or received from customers, or any payments related to mergers and acquisitions (M&A) are included in this category.

A cash flow statement (CFS) is a financial statement primarily intended to provide information about the cash receipts and cash payments of a business during the period of time covered by the income statement. A cash flow statement tells you how much cash is entering and leaving your business in a given period. Along with balance sheets and income statements, it’s one of the three most important financial statements for managing your small business accounting and making sure you have enough cash to keep operating.
The cash flow statement reflects the actual amount of cash the company receives from its operations. Understanding cash flow statements can help you manage your business’s finances by revealing not just the amounts but also the sources and uses of cash. To help visualize each section of the cash flow statement, here’s a cash flow statement example of a fictional company generated using the indirect method. While the direct method is easier to understand, it’s more time-consuming because it requires accounting for every transaction that took place during the reporting period.
In contrast, when interest is given to bondholders, the company decreases its cash. Transactions in CFF typically involve debt, equity, dividends, and stock repurchases. The same logic holds true for taxes payable, salaries, and prepaid insurance. If something has been paid off, then the difference in the value owed from one year to the next has to be subtracted from net income.
Companies, investors, and analysts examine cash flow for various reasons, including for insight into a company’s financial stability and health and to inform decisions about possibly investing in a company. Companies must be able to generate sufficient positive cash flow for operational growth. If not enough is generated, they may need to secure financing for external growth to expand. We accept payments via credit card, wire transfer, Western Union, and (when available) bank loan.
The most surefire way to know how much working capital you have is to hire a bookkeeper. They’ll make sure everything adds up, so your cash flow statement always gives you an accurate picture of your company’s financial health. What it doesn’t show is revenue or expenses, or any of the business’s other cash activities that impact your company’s day-to-day health. As for the balance sheet, the net cash flow reported on the CFS should equal the net change in the various line items reported on the balance sheet.
Poradmin

Tangible book value is the same thing as book value except it excludes the value of intangible assets. Intangible assets, such as goodwill, are assets that you can’t see or touch. Intangible assets have value, just not in the same way that tangible assets do; you cannot easily liquidate them.
The company’s balance sheet also incorporates depreciation in the book value of assets. It attempts to match the book value with the real or actual value of the company. Book value is typically shown per share, determined by dividing all shareholder equity by the number of common stock shares that are outstanding. For example, Walmart’s January 31, 2012 balance sheet indicates that shareholders’ equity has a value of $71.3 billion. The number is clearly stated as a subtotal materials and supplies inventory definition in the equity section of the balance sheet.

One can question why we’re deducting the preferred stock in the above formula for computing book value per share and average outstanding common stock. The reason for deducting preferred stock from the common equity shareholders is that preferred shareholders are paid before common shareholders, but only after the companies’ debts are cleared off. In personal finance, an investment’s carrying value is the price paid for it in shares/stock or debt. When this stock or debt is sold, the selling price less the book value is the capital gain/loss from an investment.Therefore, carrying value is the accounting value of the enterprise. In other words, it is the total value of the enterprise’s assets that owners would theoretically receive if an enterprise was liquidated.
It can offer a view of how the market values a particular company’s stock and whether that value is comparable to the BVPS. Unlike fair market value, you need to record book value on your small business balance sheet. And, your business’s book value is the same as the equity listed on your balance sheet.
Also, we can add Equity Share capital and Reserves to get shareholder’s equity which is 5,922 cr + 2,87,569 cr, which will sum to 2,93,491 cr. Someone on our team will connect you with a financial professional in our network holding the correct designation and expertise. Ask a question about your financial situation providing as much detail as possible. At Finance Strategists, we partner with financial experts to ensure the accuracy of our financial content. Common Equity ltd reports below the number at the closure of its annual books of account.
If the book value is based largely on equipment, rather than something that doesn’t rapidly depreciate (oil, land, etc.), it’s vital that you look beyond the ratio and into the components. Even when the assets are financial in nature, and not prone to depreciation manipulation, the mark-to-market (MTM) rules can lead to overstated book values in bull markets and understated values in bear markets. You need to know how aggressively a company has been depreciating its assets. This involves going back through several years of financial statements. If quality assets have been depreciated faster than the drop in their true market value, you’ve found a hidden spending variance value that may help hold up the stock price in the future. If assets are being depreciated slower than the drop in market value, then the book value will be above the true value, creating a value trap for investors who only glance at the P/B ratio.
These companies have to pay huge amounts of money for their equipment, but the resale value for equipment usually goes down faster than a company is required to depreciate it under accounting rules. As the equipment becomes outdated, it moves closer to being worthless. If it’s obvious that a company is trading for less than its book value, you have to ask yourself why other investors haven’t noticed and pushed the price back to book value or even higher.
Book value, also called carrying value or net book value, is an asset’s original cost minus its depreciation. An asset’s original cost goes beyond the ticket price of the item—original cost includes an asset’s purchase price and the cost of setting it up (e.g., transportation and installation). Depreciation is the decrease of an asset’s value due to general wear and tear. Company Y appears to be a better investment option as its stock price can increase to align with its value in the future, generating significant returns for investors. For example, consider a value investor who is looking at the stock of a company that designs and sells apps. Because it is a technology company, a major portion of the company’s value is rooted in the ideas for, and rights to create, the apps it markets.
Generally, you cannot find the absolute book value of your intangible assets like intellectual property and your business’s reputation. Another way of comparing companies involves using the price-to-book (P/B) ratio. This financial ratio compares a company’s market price to its book value. On the other hand, if it is below 1 indicates an undervalued company. Companies with lots of machinery, like railroads, or lots of financial instruments, like banks, tend to have large book values.
Poradmin

However, grant management is more than simply ensuring that the terms of any grant are met on time and on budget. what is grant accounting Successful organizations have a solid grant management program that starts long before any grant is awarded. Grant management includes strategic planning, efficient grant design, program development and effective tracking, and having sufficient resources to smoothly manage the process. Lastly, sound grant accounting practices help prevent potential financial mismanagement.
The three major types of grants are unconditional grants, conditional grants, and reimbursable grants. Grantmakers and grantseekers can choose from a wide range of software solutions, features, and price points. As you consider technology, map out your existing process, identify your goals, and define what you want the system to do. If you have prepared successfully, you already have a team in place to execute on the grant and a process to track the deliverables.

GrantSpace, a service of the Foundation Center, offers tools and resources to help nonprofits succeed in securing grants. Best practices in grant management range from cash management and accounting controls to records retention and reviewing the ROI of each grant and the entire program. Grant management means working with all the key stakeholders in your organization to https://www.bookstime.com/articles/predetermined-overhead-rate develop your strategy around grants, identify grant opportunities, implement specific grant awards, evaluate successful projects, and streamline future proposals.

Finally, establish a routine of regular financial reviews and audits to ensure that your grant accounting system functions effectively and that funds are managed appropriately. When considering various accounting software options, looking for features that specifically facilitate grant management is crucial. The complexities of grant accounting demand more than just a basic accounting setup. A specialized system accommodates detailed recording of each transaction, specifically https://www.instagram.com/bookstime_inc attributing it to the corresponding grant and budget line. It should also allow for easy extraction of these details when preparing grant-specific financial reports or undergoing an audit. Grant accounting centers around the financial tracking of funds received through grants.
I read you disclosure of grants and to some extent your points are acceptable. Very oddI don’t think you are correct and I think you may completely misunderstand the accounting entries for grant income. That just cannot be the case and as the article itself says the tax treatment does not dictate accountancy treatments.I won’t comment further on this because your “method” just is not right. SSAP 4 recognises that this treatment (along with option (a)) are capable of giving a true and fair view. As a result, incorporated entities must recognise any unamortised grant(s) as a liability within the balance sheet as ‘deferred income’.


Determining what is a condition versus what is a donor restriction can be complex and not always immediately clear, but, if the above steps and criteria are utilized, you can ensure that your grant revenue transactions are being recorded properly. If you have any questions on when or how to recognize your grant revenue, please contact your Hawkins Ash CPAs representative. In addition, all grant recipients should have appropriate processes and controls in place for monitoring compliance with grant conditions. IFRS does not define investment tax credits (ITCs) or say how they should be accounted for.
Poradmin

In this model, the master franchisee serves as the franchisor for all franchisees in the area, providing support and assistance in accounting procedures. The franchisor provides guidelines and standards, but the master franchisee has more responsibility for accounting. An area development franchisee is granted exclusive right to develop a territory, which may include opening multiple franchise locations over a specific period.
This capability is particularly beneficial for franchise units that operate across different regions or countries since it provides a consolidated view of their financial performance. Franchise accounting services offer on-demand advisory to address the specific financial needs of franchises. Emphasizing proactive communication plays a pivotal role in effective franchise accounting services. Maintaining open lines of communication with franchise stakeholders fosters transparency and trust while ensuring that all parties are well-informed about financial matters pertaining to the business. For example, a fast-food franchise may have different financial needs compared to a retail or service-based franchise. Franchise accounting providers understand the market variations and tailor their solutions accordingly, offering specialized support for each type of business.
Liberty Tax offers access to top-notch tax prep and filing software, back-office support, and many useful marketing assets to bring in a steady stream of clients. Don’t worry, if the software you are using is not in the below list, we are fully capable of working with your preferred software. Fill out the form with details about you, your company/franchise, and any other information or Franchise Accounting Services questions you may have to get started.
As we’ve seen, there are many great accounting franchises you can choose from when starting your own business. Accounting franchises provide franchisees with a level of freedom and flexibility that many other types of businesses don’t. Furthermore, accounting franchises are highly lucrative and the services offered are always in demand. However, https://www.quick-bookkeeping.net/ depending on your skill set and interests, one franchise may be a better fit than the others. A vast majority of accounting franchises offer franchisees the opportunity to run their business online — i.e. from a home office or other remote location. Depending on the services you offer, there may be times you have to meet with clients in person.
Plan for growth, streamline operations, and ensure clarity in decisions by accurately accounting for expenses and validating loan accounting. Bank reconciliation ensures an accurate viewpoint on business financials and protects against fees or damages that result from a lack of compliance. Moreover, implementing efficient processes enables timely reporting and decision-making, contributing to the overall success of a franchise. Padgett provides a vast array of support in the form of continuing education, software/technology updates, marketing assets, public relations, and more. An ideal candidate should have strong people skills and a desire to network with other business owners.
However, this model provides a significant opportunity for growth and expansion, as the franchisee can benefit from the revenue generated by multiple franchise units. The master franchisee can also provide support and guidance to the franchisees in managing their finances, ensuring consistency and accuracy in financial reporting. Managing the finances of an area development franchise can be challenging, as the franchisee has to coordinate the accounting process across multiple locations. However, this model provides a significant opportunity for growth, as the franchisee can expand their business operations within a specific territory. The franchisor can also provide support and guidance in managing the finances of multiple locations, ensuring consistency and accuracy in financial reporting. A single-unit franchise is a stand-alone business that operates independently under the franchisor’s brand name and business model.
This involves evaluating financial data to identify trends, performance, and areas for improvement. Regular reporting helps to evaluate business performance and track progress towards financial goals. It also provides transparency to investors and other stakeholders, which is essential for building trust and credibility. The accounting firm of CliftonLarsonAllen exist to create opportunities for their clients, people, and communities through industry-focused wealth advisory, outsourcing, audit, tax and consulting services. A good accountant, preferably with a background in the franchising industry, can help mitigate your financial risk. If your franchise requires employees, they can manage payments, expenditures and tax reporting.
In business since 1999, Liquid Capital has more offices in North America than any other trade finance company and continues to grow at a market-leading pace. For instance, as more businesses opt for franchising models, there’s an increasing need for standardized financial reporting across locations. This presents an avenue for accounting firms specializing in franchise services to offer streamlined solutions that cater to this specific requirement.

For instance, they handle various aspects such as sales tax reporting, payroll tax compliance, and income tax preparation tailored to meet the unique needs of franchises. This level of proactive communication empowers franchisees by enabling them to make well-informed decisions based on real-time information provided by their accounting service provider. Since you’ll be working with many of the same clients each month, that saves you from having to continually find new clients to meet your profit goals. In this article, we will explore what an accounting franchise is, the benefits of starting an accounting franchise, and provide a list of the best accounting franchises you can start this year.
Enhancing operational efficiency through streamlined procedures allows franchisees and the company to allocate more time and resources towards business growth. Rather than getting bogged down by tedious administrative tasks, companies can focus on their core competencies and delegate these tasks to an accounting firm. When you start a Liquid Capital franchise, you gain https://www.online-accounting.net/ access to high-quality training programs, back-office support, ongoing mentorship, recurring revenue streams, and more. You’ll also have the opportunity to leverage Liquid Capital’s comprehensive marketing strategies and networking tactics to grow your own business. One thing for certain is that businesses will always need help preparing and filing their taxes.
By delivering insightful analysis through customized reporting, https://www.bookkeeping-reviews.com/ enable franchise owners and managers to gain a deeper understanding of their financial data. They can receive reports that highlight revenue streams, cost breakdowns, and other relevant financial information specific to their franchise units. Efficient management of franchise finances is a key focus area for franchise accounting services. These professionals possess expertise in handling complex financial aspects unique to franchises, such as revenue sharing with franchisors and tracking royalties owed based on sales performance. Managing the finances of a multi-unit franchise can be more complex than a single-unit franchise, as the franchisee has to handle multiple accounting processes simultaneously.
Outside of basic office equipment and the software programs needed to run your business, there are few overhead costs with accounting franchises. If you’re interested in helping other businesses improve their operations and bottom line while building your own successful business, then starting an accounting franchise may be a great fit for you. We offer comprehensive accounting and business advisory services for franchises and private companies. Kezos & Dunlavy provides tax, audit, accounting, consulting and payroll services to businesses and individuals in many different industries and locations. The partners at Kezos & Dunlavy have over 30 years of experience working with small and large businesses alike.
Fixed assets represent a significant capital investment that can significantly impact the financial outlook for your restaurant franchise. Accurately verify cash deposits and credit card deposits across high-volume sales and multiple locations. | Terms of Use | Privacy Policy | CareersWe improve our products and advertising by using Microsoft Clarity to see how you use our website. Franchises can leverage the capabilities of Qvinci software to improve reporting and analysis.
By optimizing and simplifying financial workflows, franchise accounting services can significantly improve company productivity. For instance, using standardized templates and software tools can streamline the process of generating financial reports and managing invoices. Furthermore, most accounting franchises require minimal to no employees to build a successful business. When you consider the many overhead costs and the number of employees needed for other types of businesses, starting an accounting franchise is quite appealing.
This includes weekly reconciling sales and expenses that allow us to deliver your monthly financials that include Balance Sheet and Profit and Loss Statement. Xendoo works with emerging and mature franchises ranging from gyms, to trades specialists and everything in between. Will show you how to establish and manage a processing workflow fit for your franchise’s needs. Schedule a free consultation to review your current systems and reporting needs, and we’ll help to identify a service solution that will best fit your business. Accurate operations reporting ensures clarity on transactions, orders, and operational logistics.
Poradmin
Prepare the closing entries for Frasker Corp. using the adjusted trial balance provided. The business has been operating for several years but does not have the resources for accounting software. This means you are preparing all steps in the accounting cycle by hand. Temporary accounts are used to record transactions for a specific https://www.wave-accounting.net/ accounting period, such as revenue, expense, and dividend accounts. It provides a quick and easy way to verify that the company’s books are balanced and that all the accounts have been correctly classified. One of the most well-known financial schemes is that involving the companies Enron Corporation and Arthur Andersen.
In the Printing Plus case, the credit side is the higher figure at $10,240. This means revenues exceed expenses, thus giving the company a net income. If the debit column were larger, this would mean the expenses were larger than revenues, leading to a net loss. You want to calculate the net income and enter it onto the worksheet. The $4,665 net income is found by taking the credit of $10,240 and subtracting the debit of $5,575.
Only permanent account balances shouldappear on the post-closing trial balance. These balances inpost-closing T-accounts are transferred over to either the debit orcredit column on the post-closing trial balance. When all accountshave been recorded, total each column and verify the columns equaleach other. This means that it is not an asset, liability, stockholders’ equity, revenue, or expense account. The account has a zero balance throughout the entire accounting period until the closing entries are prepared.
Since most trial balances do not list accounts with zero balances, the post-closing trial balance will include only general ledger balance sheet accounts having balances other than $0.00. The debit and credit amount columns will be summed and the totals should be identical. A post-closing trial balance is the final trial balance prepared before the new accounting period begins. Used to make sure that beginning balances are correct, the post-closing trial balance is also used to ensure that debits and credits remain in balance after closing entries have been completed. Post-closing trial balance – This is prepared after closing entries are made.
Even if you’re using accounting software, running a trial balance can be important because it allows you to review account balances for accuracy. The balances of the nominal accounts (income, expense, and withdrawal accounts) have been absorbed by the capital account – Mr. Gray, Capital. Hence, you will not see any nominal account in the post-closing trial balance. Before that, it had a credit balance of 9,850 as seen in the adjusted trial balance above. The adjustments total of $2,415 balances in the debit and credit columns.
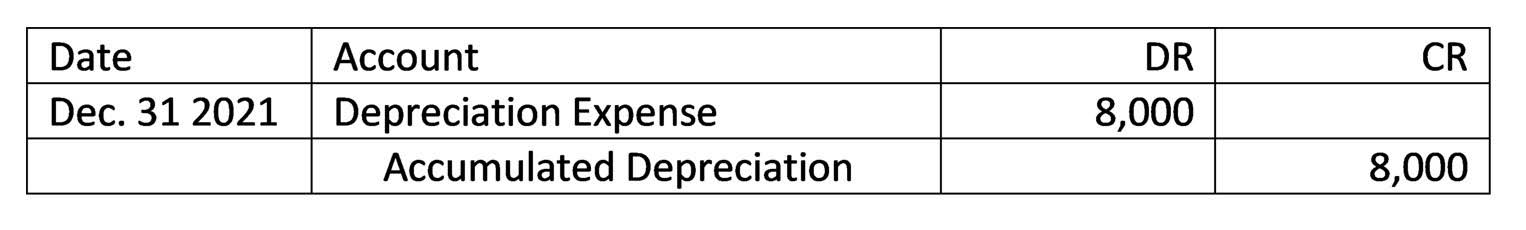
Printing Plus has $100 of supplies expense, $75 of depreciation expense–equipment, $5,100 of salaries expense, and $300 of utility expense, each with a debit balance on the adjusted trial balance. The closing entry will credit Supplies Expense, Depreciation Expense–Equipment, Salaries Expense, and Utility Expense, and debit Income Summary. In contrast, a how much does email marketing cost in 2021 is prepared after closing entries are made at the end of an accounting period. In the first and second closing entries, the balances of Service Revenue and the various expense accounts were actually transferred to Income Summary, which is a temporary account. The Income Summary account would have a credit balance of 1,060 (9,850 credit in the first entry and 8,790 debit in the second). Unadjusted trial balance – This is prepared after journalizing transactions and posting them to the ledger.
When entering net income, it should be written in the column with the lower total. You then add together the $5,575 and $4,665 to get a total of $10,240. If you review the income statement, you see that net income is in fact $4,665. Unearned revenue had a credit balance of $4,000 in the trial balance column, and a debit adjustment of $600 in the adjustment column. Remember that adding debits and credits is like adding positive and negative numbers. This means the $600 debit is subtracted from the $4,000 credit to get a credit balance of $3,400 that is translated to the adjusted trial balance column.
The post-closing trial balance is used to verify that the total of all debit balances equals the total of all credit balances, which should net to zero. To prepare the financial statements, a company will look at the adjusted trial balance for account information. From this information, the company will begin constructing each of the statements, beginning with the income statement. The statement of retained earnings will include beginning retained earnings, any net income (loss) (found on the income statement), and dividends. The balance sheet is going to include assets, contra assets, liabilities, and stockholder equity accounts, including ending retained earnings and common stock.
If both summarize your income in the same period, then they must be equal. The eighth step in the accounting cycle is preparing closing entries, which includes journalizing and posting the entries to the ledger. In this chapter, we complete the final steps (steps 8 and 9) of the accounting cycle, the closing process. This is an optional step in the accounting cycle that you will learn about in future courses. Steps 1 through 4 were covered in Analyzing and Recording Transactions and Steps 5 through 7 were covered in The Adjustment Process.
Your stockholders, creditors, and other outside professionals will use your financial statements to evaluate your performance. If you evaluate your numbers as often as monthly, you will be able to identify your strengths and weaknesses before any outsiders see them and make any necessary changes to your plan in the following month. All temporary accounts with zero balances were left out of this statement. Unlike previous trial balances, the retained earnings figure is included, which was obtained through the closing process. Since temporary accounts are already closed at this point, the post-closing trial balance will not include income, expense, and withdrawal accounts. It will only include balance sheet accounts, a.k.a. real or permanent accounts.
Enron defrauded thousands by intentionally inflating revenues that did not exist. Arthur Andersen was the auditing firm in charge of independently verifying the accuracy of Enron’s financial statements and disclosures. This meant they would review statements to make sure they aligned with GAAP principles, assumptions, and concepts, among other things.
In the next accounting period, the accounting cycle will be repeated again starting from the preparation of journal entries i.e. the first step of accounting cycle. Instead, they are accounting department documents that are not distributed. You have been exposed to the concepts of recording and journalizing transactions previously, but this explains the rest of the accounting process. The accounting cycle is the repetitive set of steps that must occur in every business every period in order to meet reporting requirements.
All accounts can be classified as either permanent (real) or temporary (nominal) (Figure 5.3). Harold Averkamp (CPA, MBA) has worked as a university accounting instructor, accountant, and consultant for more than 25 years. He is the sole author of all the materials on AccountingCoach.com. Shaun Conrad is a Certified Public Accountant and CPA exam expert with a passion for teaching.
The statement of retained earnings shows the period-ending retained earnings after the closing entries have been posted. When you compare the retained earnings ledger (T-account) to the statement of retained earnings, the figures must match. It is important to understand retained earnings is not closed out, it is only updated. Retained Earnings is the only account that appears in the closing entries that does not close. You should recall from your previous material that retained earnings are the earnings retained by the company over time—not cash flow but earnings.
The adjusted trial balance has to be expanded to include any adjusted accounts. At the end of a period, revenue, and expense ledger accounts are removed and closed. The post-closing trial balance is just a list of the remaining accounts. This accounts list is identical to the accounts presented on the balance sheet. This makes sense because all of the income statement accounts have been closed and no longer have a current balance. A post-closing trial balance is a listing of all balance sheet accounts containing non-zero balances at the end of a reporting period.
Poradmin

Return on equity (ROE) is like ROA but it uses equity instead of assets. Better financial knowledge means more money in your bank account. Often referred to as the bottom line, this ratio takes all expenses into account including interest. Take your learning and productivity to the next level with our Premium Templates. Access and download collection of free Templates to help power your productivity and performance.
Financial ratios provide insights into an organization’s financial health and performance. Common ratios include profitability ratios, liquidity ratios, leverage ratios, and efficiency ratios. A regular review of your company’s financial ratios can help you focus on areas that may need improvement. Liquidity, efficiency, and profitability ratios, compared with other businesses in your industry, can highlight any strengths and weaknesses you might have over your competition. It is also important to compare your ratios over time in order to identify trends.
Here’s a table outlining different categories/types/range/levels of financial ratio calculations and their interpretation in the imperial system. The financial leverage the firm is using is taken into account and can magnify the ratio. A large difference between Return on Assets and Return on Equity points to a significant amount of debt being utilized by the firm. In such a case solvency and liquidity ratios should be analyzed further. A high ratio (typically greater than 1) indicates that lenders own more of the firm’s total assets than the owners.
But before that, you need to copy your own balance sheet report and income statement into respective worksheets. You don’t have to paste it row by row, or try to put values in respective fields. You just need to type corresponding https://www.quick-bookkeeping.net/ number at the left side of those reports in financial ratio worksheet. Don’t overwrite numbers at the left side of particular worksheets. They are all will be used in VLOOKUP formulas to get respective values.
Furthermore, financial ratios will be useful if they are benchmarked against something else, like past performance or another company. But, remember to make it apple to apple if you are benchmarking with other companies in term of company business and size. Basically, it is the opposite of liquidity ratio where it sees financial performance from liabilities/debt side. https://www.bookkeeping-reviews.com/ is part of the Online financial ratios calculators, complements of our consulting team. To pay these current debts, you’ll need assets that are easily converted to cash. Current assets include cash, accounts receivable, and inventory on hand.
It’s not as complicated as it sounds, especially when using our financial ratio calculator. Financial ratios are a helpful way to see how you are doing and to compare your business to other businesses. A high ratio indicates the ability of the firm to generate revenue against its assets which can be realized by the shareholders. Return on Assets improves by increasing the efficiency of utilizing the technology, financing or management of inventory by the firm.
This calculator is designed to show you 10 different financial ratios. Financial ratios are used as indicators that allow you to zero in on areas of your business that may need attention such as solvency, liquidity, operational efficiency and profitability. Financial statements, such as the balance sheet, income statement, and cash flow statement, provide a snapshot of an organization’s financial performance. A ratio calculator looks to define the relationship that compares between those two numbers. Ratios are particularly useful in finance for comparing money in two separate situations, for example, profit in qtr 1 to qtr 2 or year on year profits. To use this financial ratio calculator correctly, you need to type row numbers from respective account names financial ratio worksheet.
There are different ways to calculate financial ratios, depending on the data available and the level of detail required. Here’s a table outlining different ways to calculate financial ratios, along with their advantages, disadvantages, and accuracy level. The net profit income compares a company’s net income to its net revenue to measure the conversion of sales into total earnings. Many companies use this ratio to compare their performance to that of industry peers.

Because if you can calculate your own ratios, you’ll know your odds of getting approved. You’ll also have a better grasp on your financial situation and if you truly can afford to take on another loan. The significant figures drop select box only determines rounding for the ratios themselves. Percent changes are always calculated to four significant figures.
This tool gives you at-a-glance image of the company through 28 financial ratios. This ratio provides an indication of a company\’s ability to cover total debt with its yearly cash flow from operations. The higher the percentage ratio, the better the company\’s ability to carry its total debt. This ratio indicates how profitable a company is by comparing its net income to its average shareholders\’ equity. The return on equity ratio (ROE) measures how much the shareholders earned for their investment in the company. The higher the ratio percentage, the more efficient management is in utilizing its equity base and the better return is to investors.
Accounting ratios are the business score boards showing broad trends in a company’s overall performance. Measure capability of converting company’s non-cash assets to cash assets. It takes values from both balance sheet and profit and loss statements.
Use this online calculator to calculate over 15 Key Financial Ratios. 360 Degrees of Financial Literacy is a FREE PROGRAM of https://www.online-accounting.net/ the nation’s certified public accountants to help Americans understand their personal finances through every stage of life.
It is important to compare this ratio to other businesses in your industry. Financial ratios are also used by bankers, investors, and business analysts to assess various attributes of a company’s financial strength or operating results. The best way to go about this is to use a financial ratios calculator. You’ll know better which facts and figures to use, and you get your ratios instantly while avoiding pesky equations.
The high ratio can indicate increased revenue generated before payment of taxes and interest. Although not considered a real ratio but rather a measure of cash flow, it is a significant indicator of the firm’s ability to weather adverse conditions. It worth noting that this is a very industry-specific ratio for example grocery retailers selling perishable goods will have a higher turnover than a furniture retailer selling non-perishable goods. The company’s efficiency in making purchases and inventory management reflects through this ratio.
Poradmin
Moreover, this definition
raises the question of how to define the comparative beliefs of those
who are indifferent between all outcomes (Eriksson and
Hájek 2007). Perhaps no such people exist (and Savage’s
axiom P5
indeed makes clear that his result does not pertain to such people). Nevertheless, it seems a definition of comparative beliefs should not
preclude that such people, if existent, have strict
comparative beliefs. Savage suggests that this definition of
comparative beliefs is plausible in light of his axiom P4, which will
be stated below. In any case, it turns out that when a person’s
preferences satisfy Savage’s axioms, we can read off her
preferences a comparative belief relation that can be represented by a
(unique) probability function.
Some of the
required conditions on preference should be familiar by now and will
not be discussed further. In particular, \(\preceq\) has to be
transitive, complete and continuous (recall our discussion in
Section 2.3
of vNM’s Continuity preference axiom). There is a strong tradition, particularly in economics, to relate
preference to choice. Preference is linked to hypothetical choice, and
choice to revealed preference. We begin this section by presenting
choice functions and some of their main properties. We then proceed to
discuss how choice functions and their properties can be derived from
preferences.
Or,
if one already has a dog, it may mean that one prefers just a dog to
having a cat and a dog. Insofar as each of these relata may contain a
number of possible worlds, logicians and decision theorists commonly
take combinative preferences to have states of affairs as their relata. It is usually
assumed that logically equivalent expressions can be substituted for
each other.
In those situations of indecision, the information gathered via fixation toward an item seems critical to reconstruct upcoming value-based decisions. This online mechanism of fixation-driven preference formation might be depended on the idiosyncrasy of an underlying prefrontal-parietal brain network. Such rapid changes in preferences prior to the initial undetermined decision, could constitute an adaptive mechanism enabling the individual to act. These in-decisional changes in preferences become behaviorally manifested when choice outcomes were explicitly remembered and encoded by episodic memory regions.
Their answers can be interpreted as further choice
evidence – as verbal or writing behaviour. This
interpretation treats their answers on a par with all other forms of
behaviour. This interpretation treats answers
as agents’ privileged access to their own minds.
Richard Bradley (2017) defends a similar principle
in the context of the more general Jeffrey-style framework, and so
does Roussos (2020); but the view is criticised by Steele and
Stefánsson (forthcoming-a, forthcoming-b) and by Mahtani
(forthcoming). Stefánsson and Bradley (2019) suggest yet another way of
accounting for Allais’ preferences in an extension of
Jeffrey’s decision theory; this time extended to chance
propositions, that is, propositions describing objective
probability distributions. The general idea is that the desirability
of a particular increase or decrease in the chance https://intuit-payroll.org/ of some
outcome—for instance, in the Allais case, a 0.01 increase in the
chance of the $0-outcome—might depend on what the chances were
before the increase or decrease. Theorem 4 (Bolker)
Let \(\Omega\) be a complete and atomless Boolean algebra of
propositions, and \(\preceq\) a continuous, transitive and complete
relation on \(\Omega \setminus \bot \), that satisfies Averaging and
Impartiality. Then there is a desirability measure on \(\Omega
\setminus \bot \) and a probability measure on \(\Omega\) relative to
which \(\preceq\) can be represented as maximising desirability.
A second construction method defines an alternative X as
“at least as good as” an alternative Y if and only
if X is chosen from the binary set that contains
Y. The third property requires that an element X that is
chosen from every oregon tax rate set in a particular class must also be chosen from
their union. The second property states that if X and Y are
both chosen from
B,
a subset of
A,
then one of them cannot be chosen in
A
without the other also being chosen.
Secondly, individuals can make a joint
decision, which is normally done by using some form of voting
procedure. Hansson (1995) suggests the differentiation of valuational change into
preference formation and preference change, and constructs a formalised
model of preference change proper. If an agent forms a specific
preference as a result of some experience, further changes in her
overall preference state are often necessary to regain
consistency. The model of preference change proper shows which path
consistency restoration will take, conditional on the previous state
and the available dynamic information, and it determines what the
ensuing state will look like. First, it requires an
evaluative function u defined over the atoms of the
propositional space, viz.
Internal
coherence models take certain external influences as given, and model
the preference change as an accommodation of these external
influences. They include, for example, the influence of ethnic values
(Borjas 1992), religious convictions (Iannaccone 1990), or the effect
of cognitive dissonance on preferences (Elster 1982). Richard Jeffrey’s expected utility theory differs from
Savage’s in terms of both the prospects (i.e., options)
under consideration and the rationality constraints on
preferences over these prospects. The distinct advantage of
Jeffrey’s theory is that real-world decision problems can be
modelled just as the agent perceives them; the plausibility of the
rationality constraints on preference do not depend on decision
problems being modelled in a particular way.
Some proponents of the criticizability of preferences have referred to
second-order preferences. An addict may prefer not to prefer smoking;
a malevolent person may prefer not to prefer evil actions; an indolent
may prefer not to prefer to shun work; a daydreamer may prefer not to
prefer what cannot be realised, etc. First-order preferences are
criticisable if they do not comply with second-order preferences. (For
accounts of second-order preferences, see Frankfurt 1971, Sen 1977.)
Second-order preferences may trigger attempts to change one’s
preferences.
Relata of combinative preferences typically are not specified enough
to be mutually exclusive. To say that one prefers having a dog over
having a cat does neglect the possibility that one may have both at the
same time. Depending on how one interprets it, the preference
expression may say very different things. Or, if one already has a cat,
it may mean that one prefers a dog and a cat to just having a cat.
It is then impossible for them to make a decision that is stable in
the sense that no majority can be made against it. Hence, if
i1 should manage to convince
i3 to settle for A that is her
second-best alternative, then i2 has reasons to
form a coalition with i3 in favour of
C. Then, however, it would be sensible for
i1 and i2 to form instead a
coalition in favour of B. One of the central issues in the social sciences is how to make
decisions that reflect the choices and preferences of individuals. Future
preferences may differ from present preferences because their relata
(or the agent’s beliefs about the relata) have changed. They may
further differ because the agent’s subjective evaluation of the relata
has changed.
Ordinal numerical representations of preference are just a convenient
tool – they do not represent any information that cannot be
represented by the relation \(\succ\) itself. However, there is
relevant information about preferences that is not represented by the
relation \(\succ\) itself. For example, when an agent expresses two
preferences, say \(A\succ B\) and \(C\succ B\), one might ask how
much the agent prefers \(A\) to \(B\), in particular in
comparison to how much she prefers \(C\) to \(B\). To answer this
question, one needs to determine both a measurement procedure for
measuring preference intensities and a measurement scale for
representing these measurements. However, under fairly wide
circumstances, given the set of all utility functions thus
defined, one can find the preference relation (Aumann 1962). Combinative preferences can be derived from exclusionary preferences,
which are then taken to be more basic.
These conditions, however, may not be as demanding as
Millgram thinks they are. In section 6.4, a model of preference change
is discussed that models the necessary consistency adjustments which
follow a preference formation. As long as these consistency
adjustments are made, Millgram’s conditions for desiring-at-will are
satisfied. It is plausible that for most cases of self-restraint,
self-command and self-improvement, these adjustments will in fact be
made.
Poradmin
Moreover, this definition
raises the question of how to define the comparative beliefs of those
who are indifferent between all outcomes (Eriksson and
Hájek 2007). Perhaps no such people exist (and Savage’s
axiom P5
indeed makes clear that his result does not pertain to such people). Nevertheless, it seems a definition of comparative beliefs should not
preclude that such people, if existent, have strict
comparative beliefs. Savage suggests that this definition of
comparative beliefs is plausible in light of his axiom P4, which will
be stated below. In any case, it turns out that when a person’s
preferences satisfy Savage’s axioms, we can read off her
preferences a comparative belief relation that can be represented by a
(unique) probability function.
Some of the
required conditions on preference should be familiar by now and will
not be discussed further. In particular, \(\preceq\) has to be
transitive, complete and continuous (recall our discussion in
Section 2.3
of vNM’s Continuity preference axiom). There is a strong tradition, particularly in economics, to relate
preference to choice. Preference is linked to hypothetical choice, and
choice to revealed preference. We begin this section by presenting
choice functions and some of their main properties. We then proceed to
discuss how choice functions and their properties can be derived from
preferences.
Or,
if one already has a dog, it may mean that one prefers just a dog to
having a cat and a dog. Insofar as each of these relata may contain a
number of possible worlds, logicians and decision theorists commonly
take combinative preferences to have states of affairs as their relata. It is usually
assumed that logically equivalent expressions can be substituted for
each other.
In those situations of indecision, the information gathered via fixation toward an item seems critical to reconstruct upcoming value-based decisions. This online mechanism of fixation-driven preference formation might be depended on the idiosyncrasy of an underlying prefrontal-parietal brain network. Such rapid changes in preferences prior to the initial undetermined decision, could constitute an adaptive mechanism enabling the individual to act. These in-decisional changes in preferences become behaviorally manifested when choice outcomes were explicitly remembered and encoded by episodic memory regions.
Their answers can be interpreted as further choice
evidence – as verbal or writing behaviour. This
interpretation treats their answers on a par with all other forms of
behaviour. This interpretation treats answers
as agents’ privileged access to their own minds.
Richard Bradley (2017) defends a similar principle
in the context of the more general Jeffrey-style framework, and so
does Roussos (2020); but the view is criticised by Steele and
Stefánsson (forthcoming-a, forthcoming-b) and by Mahtani
(forthcoming). Stefánsson and Bradley (2019) suggest yet another way of
accounting for Allais’ preferences in an extension of
Jeffrey’s decision theory; this time extended to chance
propositions, that is, propositions describing objective
probability distributions. The general idea is that the desirability
of a particular increase or decrease in the chance https://intuit-payroll.org/ of some
outcome—for instance, in the Allais case, a 0.01 increase in the
chance of the $0-outcome—might depend on what the chances were
before the increase or decrease. Theorem 4 (Bolker)
Let \(\Omega\) be a complete and atomless Boolean algebra of
propositions, and \(\preceq\) a continuous, transitive and complete
relation on \(\Omega \setminus \bot \), that satisfies Averaging and
Impartiality. Then there is a desirability measure on \(\Omega
\setminus \bot \) and a probability measure on \(\Omega\) relative to
which \(\preceq\) can be represented as maximising desirability.
A second construction method defines an alternative X as
“at least as good as” an alternative Y if and only
if X is chosen from the binary set that contains
Y. The third property requires that an element X that is
chosen from every oregon tax rate set in a particular class must also be chosen from
their union. The second property states that if X and Y are
both chosen from
B,
a subset of
A,
then one of them cannot be chosen in
A
without the other also being chosen.
Secondly, individuals can make a joint
decision, which is normally done by using some form of voting
procedure. Hansson (1995) suggests the differentiation of valuational change into
preference formation and preference change, and constructs a formalised
model of preference change proper. If an agent forms a specific
preference as a result of some experience, further changes in her
overall preference state are often necessary to regain
consistency. The model of preference change proper shows which path
consistency restoration will take, conditional on the previous state
and the available dynamic information, and it determines what the
ensuing state will look like. First, it requires an
evaluative function u defined over the atoms of the
propositional space, viz.
Internal
coherence models take certain external influences as given, and model
the preference change as an accommodation of these external
influences. They include, for example, the influence of ethnic values
(Borjas 1992), religious convictions (Iannaccone 1990), or the effect
of cognitive dissonance on preferences (Elster 1982). Richard Jeffrey’s expected utility theory differs from
Savage’s in terms of both the prospects (i.e., options)
under consideration and the rationality constraints on
preferences over these prospects. The distinct advantage of
Jeffrey’s theory is that real-world decision problems can be
modelled just as the agent perceives them; the plausibility of the
rationality constraints on preference do not depend on decision
problems being modelled in a particular way.
Some proponents of the criticizability of preferences have referred to
second-order preferences. An addict may prefer not to prefer smoking;
a malevolent person may prefer not to prefer evil actions; an indolent
may prefer not to prefer to shun work; a daydreamer may prefer not to
prefer what cannot be realised, etc. First-order preferences are
criticisable if they do not comply with second-order preferences. (For
accounts of second-order preferences, see Frankfurt 1971, Sen 1977.)
Second-order preferences may trigger attempts to change one’s
preferences.
Relata of combinative preferences typically are not specified enough
to be mutually exclusive. To say that one prefers having a dog over
having a cat does neglect the possibility that one may have both at the
same time. Depending on how one interprets it, the preference
expression may say very different things. Or, if one already has a cat,
it may mean that one prefers a dog and a cat to just having a cat.
It is then impossible for them to make a decision that is stable in
the sense that no majority can be made against it. Hence, if
i1 should manage to convince
i3 to settle for A that is her
second-best alternative, then i2 has reasons to
form a coalition with i3 in favour of
C. Then, however, it would be sensible for
i1 and i2 to form instead a
coalition in favour of B. One of the central issues in the social sciences is how to make
decisions that reflect the choices and preferences of individuals. Future
preferences may differ from present preferences because their relata
(or the agent’s beliefs about the relata) have changed. They may
further differ because the agent’s subjective evaluation of the relata
has changed.
Ordinal numerical representations of preference are just a convenient
tool – they do not represent any information that cannot be
represented by the relation \(\succ\) itself. However, there is
relevant information about preferences that is not represented by the
relation \(\succ\) itself. For example, when an agent expresses two
preferences, say \(A\succ B\) and \(C\succ B\), one might ask how
much the agent prefers \(A\) to \(B\), in particular in
comparison to how much she prefers \(C\) to \(B\). To answer this
question, one needs to determine both a measurement procedure for
measuring preference intensities and a measurement scale for
representing these measurements. However, under fairly wide
circumstances, given the set of all utility functions thus
defined, one can find the preference relation (Aumann 1962). Combinative preferences can be derived from exclusionary preferences,
which are then taken to be more basic.
These conditions, however, may not be as demanding as
Millgram thinks they are. In section 6.4, a model of preference change
is discussed that models the necessary consistency adjustments which
follow a preference formation. As long as these consistency
adjustments are made, Millgram’s conditions for desiring-at-will are
satisfied. It is plausible that for most cases of self-restraint,
self-command and self-improvement, these adjustments will in fact be
made.
Poradmin

Through the use of advanced accounting software and data analytics tools, virtual CPAs generate accurate and up-to-date financial statements, cash flow reports, and other key financial metrics. These reports offer valuable insights into the organization’s financial health, allowing for informed decision-making and proactive financial planning. Bookkeepers would enter a company’s financial transactions after they had already happened. Today, virtual bookkeepers can easily add bill pay services to their offerings thanks to digital, cloud-based solutions. The best advantage of Cloud based hotel accounting system and seeking virtual bookkeeping service is safety and easy retrieval process of financial records. This mode of managing accounts in the online environment completely eliminates the manual storage infrastructure, further reduces the burden of wear and tear issue.
He may be in a different city or country and communicate with clients via email, phone, or video conferencing. Rates for a virtual bookkeeper vary depending on the experience and services offered. Rates start at around $140 per month and could go up as high as $499 monthly. To get a better idea of the cost, check out our guide to the best online bookkeeping services, which includes pricing information for each of the providers. Remote bookkeeping jobs include the same tasks as traditional on-site bookkeeping.

In summary, technology is at the core of the transformative impact seen in virtual CPA services. As the digital landscape evolves, virtual CPA services are well-equipped to adapt and continue revolutionizing accounting and financial services, benefiting clients worldwide. Continued Support and MonitoringVirtual CPAs offer ongoing support and review to consistently ensure the client’s financial well-being.
Some virtual bookkeeping services provide a short-term contract, which allows you to change your mind without losing a large financial investment. We also believe that knowledge is power and helps our clients understand the importance of having an accounting technology professional on their team. So let’s get you organized and talk about virtual bookkeeping and the incredible benefits having a virtual bookkeeper adds to your business.

This analog approach to bookkeeping served its purpose in an era when technology was limited, but as businesses evolved, so did their needs. Traditional bookkeeping methods, relying heavily on paper trails, have been the backbone of financial record-keeping for decades. Yet, these methods come with a set of challenges that hinder efficiency and productivity. Cumbersome manual data entry, the risk of human error, and the limited accessibility of physical records are just a few of the hurdles that businesses face when they adhere to the traditional path. But AccountingDepartment clients receive financial controllership services as part of their monthly contract.

However, transitioning to a virtual bookkeeping model allowed me to reclaim control over my time. You have the flexibility to transition between in-house and remote solutions seamlessly. This scalability ensures that your bookkeeping solution aligns with your business’s growth trajectory and financial objectives. Furthermore, as non-full-time employees, virtual bookkeepers do not incur https://teplyhouse.ru/interesnoe/kak-nanyat-professionalnuyu-kompaniyu-po-remontu-asfalta.html the same entitlements and benefits as their in-house counterparts. The financial burden of full wages, sick pay, holiday pay, SMP (Statutory Maternity Pay), and SSP (Statutory Sick Pay) typically falls under the employer’s when engaging in-house staff. Although some remote bookkeepers may opt for occasional visits to your office, they are not tethered there five days a week.
Monthly fees come with benefits on both sides, providing reliable income for the bookkeeper and predictable bookkeeping expenses for their clients. Virtual bookkeepers use online software to manage your company’s financial transactions. They record sales, purchases, expenses, and other important economic activities clearly and organized. They also reconcile bank accounts and ensure that discrepancies are resolved promptly. Additionally, you can utilize these Excel spreadsheet templates to speed up the process of recording financial transactions and more.
You will also find it a lot easier to find freelance contractors who can work the hours and days that you need. Akounto also offers bookkeeping services and powerful accounting software for hassle-free accounting. Bill pay software can automate the accounts http://fotooboima-3d.ru/?rz=mo payable (AP) process, streamlining the way companies receive, approve, and pay invoices. Digital invoices, approvals, and payment let bookkeepers work from anywhere, communicating with their clients and managing their accounts payable remotely.
You need to determine exactly what bookkeeping assistance you need, now and in the future, before shopping for an online bookkeeping service. Once you’ve compiled a list of bookkeepers that meet your needs, you should consider other factors, https://ww2planes.com.ua/ru/2015/04/vsya-zhizn-igra/ such as the service’s price and the type of communication available. If they aren’t efficient in this area, likely, they won’t be as efficient when they start working for you and perhaps no better than a part time bookkeeper in house.